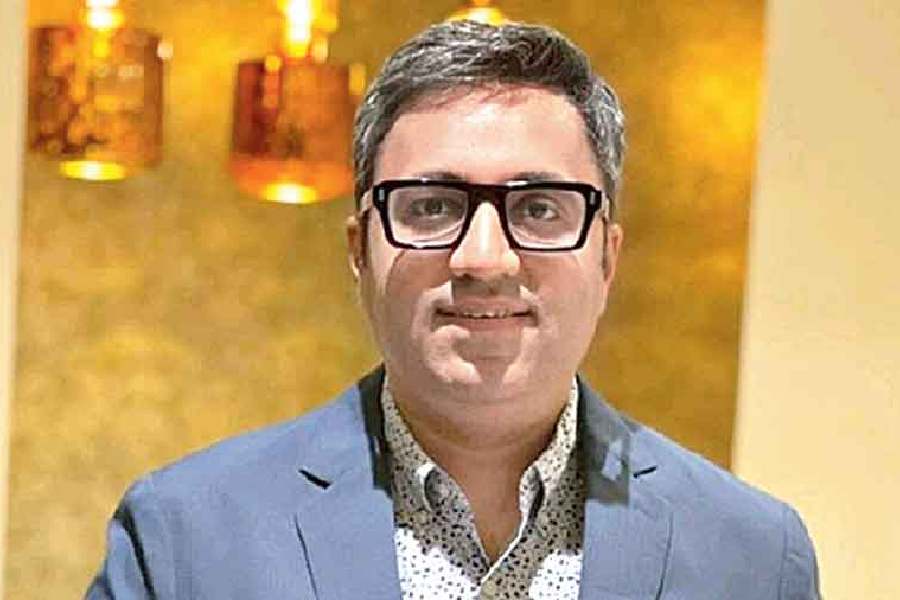
Entrepreneur and former BharatPe co-founder Ashneer Grover has questioned the proposed merchant fee on certain high-value UPI transactions, arguing that costs introduced into the payment ecosystem could eventually affect consumers.
Grover’s remarks came after the government clarified that the proposed Merchant Discount Rate (MDR) would apply to certain merchant transactions above ₹2,000, while person-to-person UPI payments would continue to remain free regardless of the transaction value.
The debate has gained attention because UPI has traditionally been associated with zero-cost digital payments for users. The proposed changes have therefore raised questions about how payment-related costs could be distributed among merchants, banks, payment companies and customers.
Grover questions description of UPI merchant charge
Speaking during a television interview, Grover challenged the argument that the new fee would not affect customers simply because it would initially be charged within the merchant payment ecosystem.
He questioned why such a levy should be described as a merchant charge or MDR rather than a tax if its economic impact eventually reaches consumers.
Grover argued that businesses facing additional payment costs could potentially factor those expenses into their pricing decisions. In such a situation, the customer could indirectly bear part of the cost even if no additional amount is formally deducted from the customer’s UPI account.
He used an analogy involving everyday expenses to question the reasoning that a charge is acceptable merely because the person or business paying it can afford it.
What is the proposed UPI MDR?
The Merchant Discount Rate is a fee associated with certain digital payment transactions. Under the proposed framework, a merchant fee will apply to UPI payments above ₹2,000 under specified conditions.
The government has maintained that MDR is not a tax and that the amount is not collected as government revenue or by the National Payments Corporation of India.
The distinction is important because a tax is imposed by the government as a compulsory public revenue measure, whereas MDR is a payment-related fee within the financial transaction ecosystem.
The proposed merchant charge is scheduled to come into effect from October 15.
Government says most merchant transactions will remain unaffected
The government has also said that the new framework will not affect the overwhelming majority of merchant transactions.
According to the clarification, around 96% of merchant transactions are expected to remain outside the impact of the charge because they either fall below the ₹2,000 threshold or are covered under the zero-MDR framework applicable to small merchants.
Person-to-person UPI transactions will also remain free irrespective of the amount involved.
This means that the proposed change is primarily focused on a specific category of merchant payments rather than introducing a fee on all UPI transactions.
Grover raises questions over UPI economics
Grover also referred to figures concerning the financial position of various institutions while questioning the justification for introducing merchant charges.
In a separate social media post, he cited figures for the Reserve Bank of India’s surplus, profits of listed banks and the pre-tax surplus reported by NPCI. He used these figures to question the argument surrounding the cost of operating the UPI ecosystem and the need for additional charges.
Grover also highlighted the expenses associated with maintaining traditional cash infrastructure, including ATMs and cash logistics. He argued that digital payments have reduced the dependence on physical cash infrastructure and questioned the broader economic rationale behind introducing additional costs for UPI transactions.
His comments reflect a wider debate about how India’s rapidly expanding digital payment infrastructure should be funded while keeping transactions affordable for users and merchants.
Why the merchant fee debate matters
UPI has become a major part of India’s digital payments ecosystem, allowing customers to make instant bank-to-bank payments using mobile applications. Its widespread adoption has been supported by the absence of direct charges for many users.
Introducing fees in parts of the merchant ecosystem could therefore influence how businesses manage digital payment costs.
The key question is whether merchants will absorb the additional expense themselves or adjust their pricing to account for it. The answer could vary depending on the size of the business, profit margins, competition and the nature of the products or services being sold.
A merchant operating in a highly competitive market may have limited ability to increase prices, while businesses with greater pricing flexibility could potentially incorporate additional payment costs into their overall pricing structure.
Consumer impact remains a central question
The government has maintained that consumers will not face a direct charge under the new framework, particularly because person-to-person payments remain free and most merchant transactions are expected to remain unaffected.
Grover, however, has raised a different issue: the possibility of indirect consumer impact.
His argument is that even when a fee is formally imposed on a business rather than a customer, the economic cost can potentially move through the supply chain. Businesses may account for higher operating expenses when setting prices, meaning consumers could eventually encounter higher prices without being directly charged a UPI fee.
Whether that happens in practice will depend on how merchants, payment providers and other participants respond after the new framework takes effect.
UPI’s next phase
The discussion surrounding merchant fees highlights a broader challenge for India’s digital payments ecosystem: maintaining the convenience and affordability of UPI while ensuring that the infrastructure supporting the system remains financially sustainable.
With the merchant charge set to take effect from October 15, attention is likely to remain focused on how banks, payment companies and merchants respond to the changes.
For consumers, the immediate distinction remains important: the proposed fee is aimed at specified merchant transactions above ₹2,000 and does not introduce a general charge on person-to-person UPI transfers.
Grover’s comments have nevertheless added another dimension to the debate by focusing on the possibility that costs imposed within the payment ecosystem could eventually influence the prices paid by consumers.